Finance the Florida land, construction, and permanent mortgage together
Build a Home in Florida With a VA One-Time Close Loan
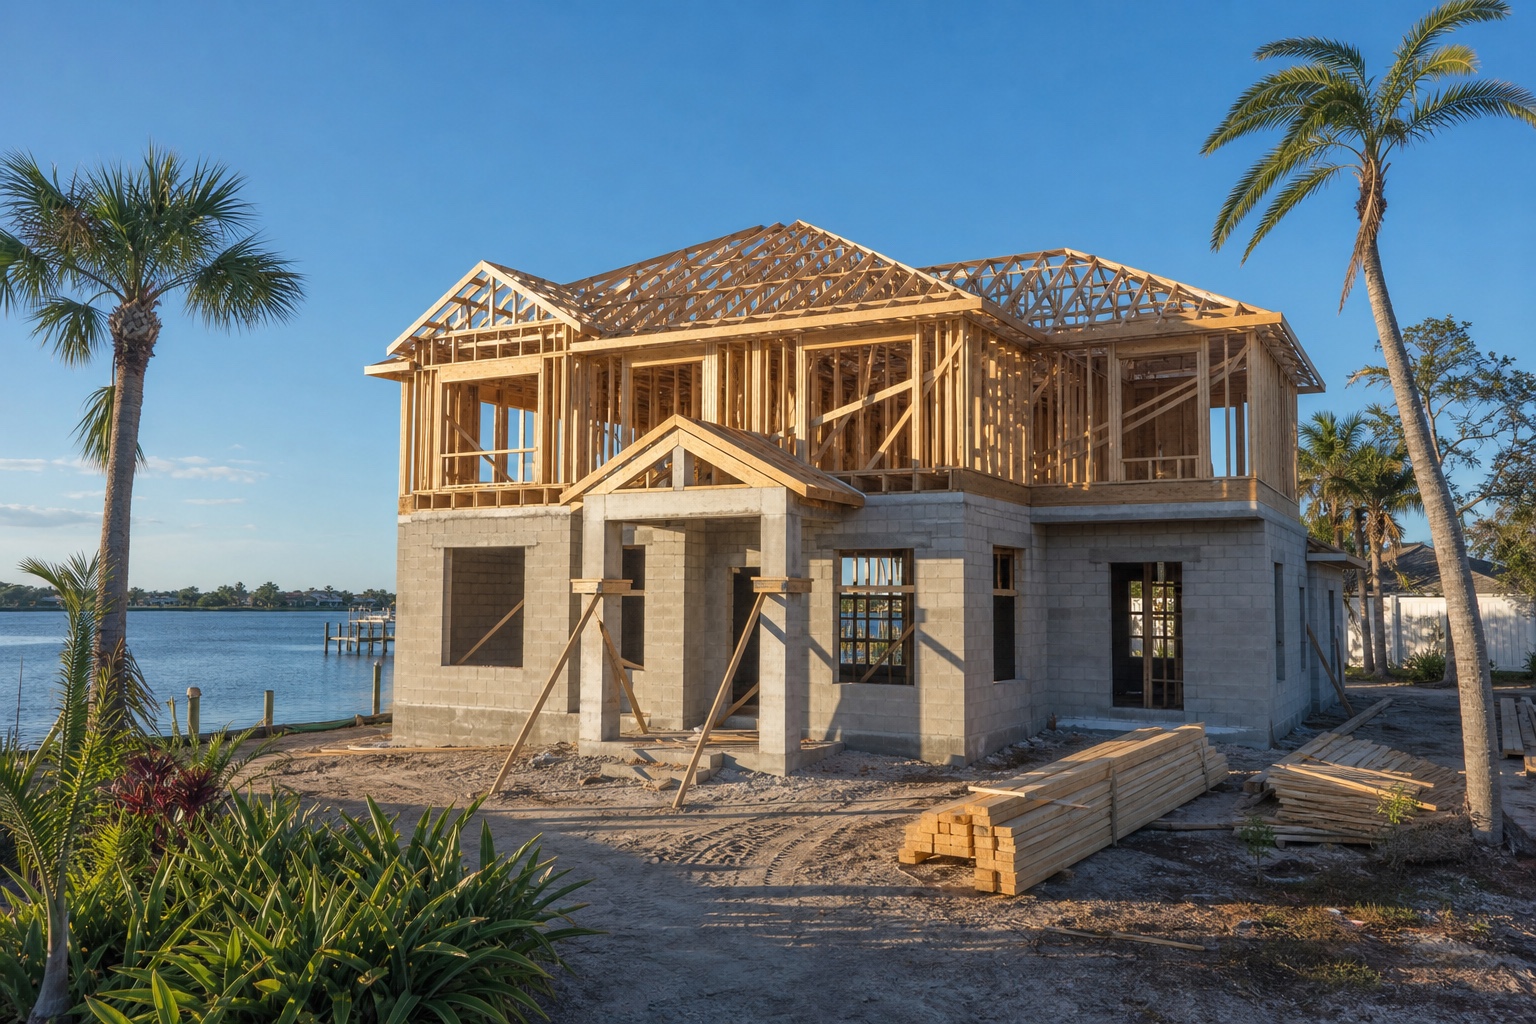
From a coastal homesite to an inland lot, your Florida home can be built around the layout and space you want. VA construction financing also means no monthly mortgage insurance on your loan.
PBT can finance the lot and new home together, with one closing for construction and the permanent mortgage. Apply online to get pre-qualified for your Florida build.
- One closing for a Florida build
Want us to look at your VA loan options?
Tell us what you are working on and the best number to reach you. We will call, answer your question, and show you the next step. You do not need a credit check to ask.
What are you trying to do?
Thanks. We will call you back shortly.
Prefer not to wait? Call 888-435-7315.
Can Florida land and the new home be financed together?
You can buy the Florida lot and build the home with the same VA loan. If you already own the land, eligible equity may reduce how much you need to borrow or bring to closing.
Land already owned
The appraised land value, less any existing payoff, helps establish the equity available for the project. We show owned-land equity separately from construction costs.
Lot purchased with the build
The lot purchase and home construction can be financed in one closing, so you do not need a separate land loan.
Vacant land for later
A VA loan cannot finance vacant Florida land by itself for a future project. The lot and residence must be part of the same approved construction transaction.
One VA loan for the home you want
Get pre-qualified for your Florida build
If the Florida homes you are touring all need changes, building lets you choose the layout from the beginning. You can apply for financing before committing to a builder.
Who can use a Florida VA construction loan?
This program is for an eligible Veteran’s new primary residence. Apply online to get pre-qualified; we pull your Certificate of Eligibility (COE) as part of the loan review.
- Available VA entitlement for the proposed loan
- Credit scores as low as 580 may be considered after a full financial review
- A loan amount supported by your finances and the completed-home appraisal
- A construction schedule of no more than 11 months plus the modification period
- An independent licensed contractor instead of an owner-builder arrangement
Does your Florida builder qualify for the program?
VA Circular 26-25-1 removed the VA Builder ID requirement. The contractor still needs the appropriate Florida license and PBT approval for your build.
Experience building new homes
The construction company must have been operating for at least three years and completed at least 10 homes, including five built from the ground up.
Florida contractor license
Florida’s Department of Business and Professional Regulation provides the license status and the type of work the contractor is licensed to perform.
Approval for your home
The builder submits a completed questionnaire, license, insurance, project history, and references for our review. Your home’s plans, signed contract, and budget are approved separately before closing. State licensing alone does not approve a builder for the loan.
Independent general contractor
Our current program requires an independent general contractor, so you cannot act as your own builder.
Which costs do we include in the Florida construction budget?
We build the budget around the complete project rather than using only the contractor’s base price.
Land and existing payoff
The budget starts with the approved lot price or current land payoff. We show owned-land equity separately from construction costs.
Hard and soft construction costs
The construction budget includes labor, materials, permits, and professional design or engineering. It also needs site work, utilities, impact fees, and draw-management costs.
Required contingency
A 5% contingency covers unexpected construction costs. After we reconcile the final account, any unused loan-funded portion reduces your loan balance. A reserve you paid in cash follows the construction contract.
Construction interest and insurance
Estimated construction interest and required builder’s risk coverage also belong in the approved construction budget.
VA funding fee and cash items
The VA funding fee or confirmed exemption completes the loan-cost side of the budget, along with any charge that cannot be financed and must be paid separately.
How do Florida permits, wind, flood, and insurance affect the loan?
The plans, permits, appraisal, and insurance must all describe the same completed home and location.
Current statewide code
The 8th Edition 2023 Florida Building Code took effect December 31, 2023. Local amendments and the building department requirements for the property also apply.
Permits and inspections
Local building departments control permit issuance and required inspections, and the draw schedule should follow the approved plans and verifiable construction milestones.
Wind and flood design
Coastal wind exposure, flood elevation, drainage, foundation, roof attachment, and opening-protection requirements can change the design, budget, appraisal, and schedule.
Different policies cover construction and the completed home
Builder’s risk protects the work during construction under its terms. It does not replace required permanent homeowners, wind, or flood coverage.
Keep the financing together
Ready to turn your Florida home plans into a new home?
One VA closing can cover the land, construction, and permanent mortgage. Start your application without having to arrange a separate mortgage after the house is finished.
Which Florida home types can we consider?
You can use the program for more than a traditional site-built house. Each home still needs to meet the construction-loan and appraisal requirements.
Site-built home
Build a primary residence from approved plans with an independent contractor. The completed home must meet the applicable building code and VA property requirements.
Modular construction
For modular construction, the permanent foundation and completed-home appraisal are important to loan eligibility. Site work and installation still belong in the project budget.
Manufactured home
A new manufactured home may qualify on a permanent foundation. Its title, installation, and appraisal must meet the program’s property requirements.
Barndominium or unique design
A barndominium or another unique design may be considered when the appraisal has acceptable comparable sales and the plans meet the program and building-code requirements.
What if the Florida construction price or schedule changes?
If the price or schedule changes after closing, we review the change before the work is completed. The loan amount may not increase, and a longer construction period may require updated financial or property documents and another approval.
Current sources for the VA loan, builder, building code, and liens
Where can you check Florida building and loan requirements?
These official sources explain Florida contractor licensing, building codes, and construction liens. The PBT guides cover the financing and project budget.
VA home loan
VA home-buying guide
The VA guide covers entitlement, occupancy, appraisal, funding fee, and purchase-loan requirements.
Open the VA guide
VA builder rule
Circular 26-25-1
This VA circular removed the VA Builder ID requirement.
Open the circular
Florida contractor
Construction license information
Florida’s licensing database lists contractor license status and business information.
Check contractor licensing
Florida code
Florida Building Code
The state site lists the current building code, effective dates, and technical resources.
Open building code
Florida liens
Chapter 713 construction liens
Chapter 713 covers the Notice of Commencement, construction lien rights, and payment rules.
Read Chapter 713
Construction guide
VA one-time-close guide
The national guide explains the current program terms, eligible costs, draw process, and payment timing.
Open the national guide
Builder review
VA builder review guide
Builder guidance explains how we review the contractor, contract, insurance, schedule, and draws.
Open the builder guide
Budget review
VA construction budget worksheet
Use the budget worksheet to list the land, construction costs, contingency, interest, insurance, and cash needed.
Open the budget worksheet
Florida purchase
VA home loans in Florida
Buying an existing Florida home is covered in the state purchase guide.
Open the state guide
Funding fee
VA funding fee chart
Current purchase and construction funding-fee rates and exemptions are listed in the fee chart.
Open the fee chart
Florida VA construction loan questions
Who offers VA construction financing for a new Florida home?
PBT Bancorp offers VA one-time close construction financing in Florida, including the lot purchase when it is part of your approved home build. You can build without monthly mortgage insurance, subject to borrower and project approval.
Can I buy Florida land and build with one VA loan?
The lot can be acquired with the approved build in one construction-to-permanent transaction. A VA loan cannot finance vacant land alone for a project that will happen later.
Can owned Florida land count toward the construction project?
Equity in land you already own can help with the financing, depending on its appraised value and any existing payoff. The equity is a financing credit, not a duplicate construction cost.
What sets the maximum loan amount for a Florida land-and-build project?
The loan amount comes from the verified income, monthly debts, VA entitlement, project budget, and finished-home appraisal. It also has to leave room for site work, permits, insurance, and the other costs required to finish the home.
Does a Florida contractor still need a VA Builder ID?
VA Circular 26-25-1 removed the Builder ID requirement, but the contractor still needs appropriate Florida licensing. We must also approve the contractor, contract, insurance, and specific project before closing.
How does my Florida builder get approved?
Your contractor sends us the builder questionnaire with their Florida license, insurance, project history, and references. Our current construction program requires the construction company to have been operating for at least three years and completed at least 10 homes, including five ground-up builds. Builder approval is separate from the review of your home’s plans, signed construction contract, and budget, and both are required before closing.
What does a Florida Notice of Commencement do?
It identifies the construction project and participants in the public record under Florida’s construction lien law. It does not replace the inspections and payment documentation required for construction draws.
Are regular mortgage payments billed during construction?
Estimated construction interest is included in the approved project budget, so regular principal-and-interest payments do not begin during the build. Scheduled permanent payments start after the home is completed and the loan is modified.
Does builder’s risk replace Florida wind or flood insurance?
No, builder’s risk covers the work during construction according to its terms. It does not replace the permanent homeowners, wind, or flood protection required for the completed property.
Can Florida modular, manufactured, or barndominium projects qualify?
Modular, manufactured, and barndominium homes may qualify when the finished home meets the program’s property and appraisal requirements. A permanent foundation and acceptable comparable sales are important for these projects.
Ready to start a Florida VA construction loan?
Start your application for a new Florida home with the rooms and layout you want.
Last reviewed August 6, 2026. PBT Bancorp NMLS #257781.